Contents 12 sections
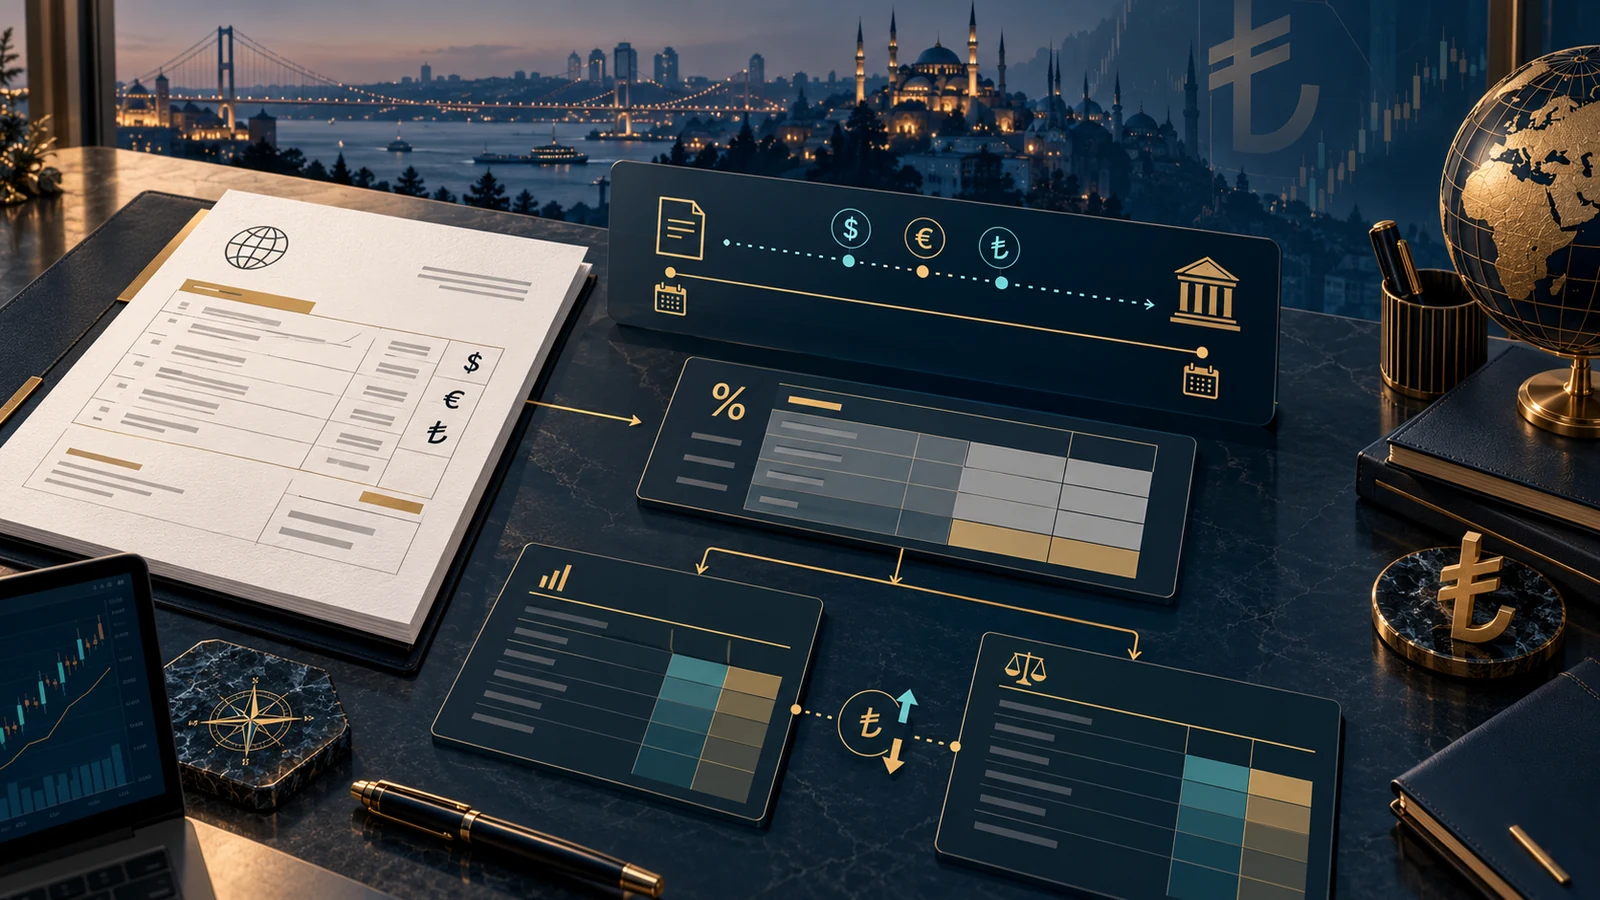
A foreign-currency invoice in Turkey can create three different Turkish-lira amounts: the amount recorded when the taxable event occurs, the amount settled when payment is made, and the amount shown after a period-end revaluation. These figures should not be forced into one calculation. The accounting team must first identify which date, exchange-rate basis and VAT treatment belongs to each stage.
For a Turkish domestic supply priced in foreign currency, a realised exchange difference arising between the supply and settlement can affect the VAT base and require an exchange-difference invoice. A difference created only by a statutory period-end valuation is different: it is an accounting valuation, not a new supply or settlement, and the current VAT General Implementation Communiqué states that VAT is not calculated on that valuation difference.
The control question: settlement or valuation?
A bank payment or collection can realise an exchange difference. A month-end, provisional-tax-period or year-end remeasurement of an unpaid balance is only a valuation step. Label the event correctly before deciding whether an invoice and VAT are required.
Review the transaction with an English-speaking Turkish tax adviser
Start with the transaction, not the currency symbol
The fact that an invoice is denominated in USD, EUR, GBP or another currency does not determine its VAT status. Before calculating any exchange difference, classify the underlying transaction:
- Domestic Turkish sale or purchase: determine the taxable event, the original VAT rate or exemption, and the Turkish-lira value entered in the statutory books.
- Sale to a customer abroad: determine whether the transaction is an export of goods, an export of services, another exemption, or an ordinary taxable supply. A foreign customer or foreign currency does not create an exemption by itself.
- Purchase from a supplier abroad: determine whether customs import VAT, reverse-charge VAT, withholding tax or another rule applies. A foreign supplier normally does not issue a Turkish domestic exchange-difference invoice.
- Loan, deposit or non-supply balance: do not automatically apply the invoicing rules for a sale of goods or services. The legal and tax character of the balance must be reviewed separately.
This classification prevents a common error: applying the domestic exchange-difference invoice rule to every foreign-currency movement, including overseas supplier balances, shareholder funding or period-end revaluations.
Which exchange rate belongs to the original invoice?
Article 26 of the Turkish VAT Law requires a foreign-currency consideration to be translated into Turkish lira at the current rate when the taxable event occurs. The contract, supply date, invoice date and the rate printed on the document should therefore be reviewed together. The taxable-event date should not be replaced casually by the payment date.
Under the Tax Procedure Law, Turkish statutory records are generally maintained in Turkish lira. A foreign-currency invoice issued to a domestic customer should generally also show the Turkish-lira equivalent, while an invoice issued to a customer abroad is treated differently under the document rule. The practical invoice file should retain:
- the original currency and amount;
- the supply or service date that creates the tax point;
- the invoice date and number;
- the exchange rate used and its source;
- the Turkish-lira taxable base and VAT amount;
- the VAT rate, exemption or withholding code; and
- the contract clause if the parties agreed a specific conversion method.
For the wider document requirements, see Turkish Invoice Requirements and Common Errors. The invoice rate, statutory revaluation rate and settlement rate should remain separate fields in the accounting data.
VAT treatment when payment creates an exchange difference
The VAT General Implementation Communiqué treats a favourable exchange difference arising after the taxable event and before collection as part of the VAT base for the original domestic supply. The calculation uses the exchange difference attributable to the goods or services; the exchange movement on the VAT amount itself is not added again to the taxable base.
| Event | Document direction | VAT control |
|---|---|---|
| Seller has a favourable realised difference on collection | Seller issues the exchange-difference invoice to the buyer | Apply the VAT treatment and rate of the original supply |
| Buyer has a favourable realised difference on payment | Buyer issues the exchange-difference invoice to the seller | Apply the VAT treatment and rate of the original supply |
| Unpaid balance is revalued at a statutory period end | No exchange-difference invoice merely for the valuation | No VAT on the valuation difference |
| Foreign customer or supplier balance | Review the cross-border document and evidence rules; do not copy the domestic route automatically | Follow the underlying export, import or reverse-charge treatment |
If the original transaction is exempt, subject to VAT withholding or outside the scope of Turkish VAT, the exchange-difference document should not be assigned an ordinary VAT rate merely because a lira difference exists. The original transaction code and supporting legal basis must be carried into the review. The broader framework is explained in the Turkey VAT Guide 2026.
Worked reconciliation: partial settlement of a domestic invoice
Assume a Turkish supplier invoices a Turkish customer for EUR 20,000 plus the applicable VAT. The statutory invoice entry is translated into Turkish lira using the documented rate for the taxable event. The customer later pays EUR 12,000 and leaves EUR 8,000 outstanding.
- Allocate the payment: link the EUR 12,000 payment to the exact invoice rather than closing the oldest balance automatically without evidence.
- Calculate the realised portion: compare the Turkish-lira carrying amount of the EUR 12,000 portion with the Turkish-lira settlement value.
- Separate the VAT component: calculate the exchange-difference taxable base only on the goods or services amount, following the current Communiqué.
- Determine direction: identify whether the realised movement favours the seller or the buyer and therefore who issues the document.
- Leave the open portion open: the remaining EUR 8,000 continues as a foreign-currency receivable or payable and is revalued at the relevant statutory valuation dates.
The team should not calculate the difference on the full EUR 20,000 when only EUR 12,000 was settled. It should also not invoice the temporary period-end revaluation of the remaining EUR 8,000.
Settlement differences and period-end revaluation are not interchangeable
Do not invoice an unrealised valuation difference
A provisional-tax-period or year-end revaluation updates the Turkish-lira carrying amount of an unpaid foreign-currency asset or liability. It does not represent a new delivery, service or payment. Record the valuation through the appropriate accounting voucher and retain the rate evidence; do not create a customer or supplier invoice solely to clear that entry.
Article 280 of the Tax Procedure Law applies valuation principles to foreign currency and foreign-currency receivables and payables. Where the Ministry has not published a rate for the valuation date, the official guidance refers to Central Bank rates under the applicable rules. The accounting team should preserve the rate table used for each close rather than relying on a rate that can later change in the ERP.
When the receivable or payable is eventually settled, the realised difference should be calculated against the carrying amount and the settlement record. The period-end valuation entries already posted must be reversed or carried forward consistently so that the final realised gain or loss is not duplicated.
Domestic and cross-border balances require different evidence
A domestic Turkish invoice normally creates a two-party Turkish document trail. For a foreign customer, the Revenue Administration has stated in a case-specific ruling that a separate Turkish invoice or similar document is not required merely to substantiate the exchange gain or loss on collection, including period-end valuation differences. That ruling should not be expanded beyond its facts, and the original export or service-export evidence must still remain complete.
For an overseas supplier, the accounting file should connect the foreign invoice, the nature and place of the service or goods, customs records where relevant, reverse-charge VAT review, bank payment and foreign-exchange entry. The overseas supplier's inability to issue a Turkish exchange-difference invoice does not eliminate the need to book a realised gain or loss correctly.
Foreign-owned businesses can place this within a broader local close framework using the Turkey Business Tax and Accounting Guide for Investors.
Evidence for an exchange-difference invoice
A reliable file lets another reviewer reproduce the amount without asking how the ERP arrived at it. Retain:
- the original invoice XML and readable copy;
- the contract, order or pricing confirmation;
- the supply or service-completion evidence;
- the original currency, tax point, invoice rate and Turkish-lira posting;
- the bank statement, value date, currency amount, bank fees and net settlement;
- the payment allocation to individual invoices;
- the rate source used at settlement;
- the calculation separating the net supply amount from VAT;
- the exchange-difference invoice or the documented reason no invoice is required; and
- the accounting voucher and VAT return mapping.
For e-Invoice and e-Archive workflows, retain the original electronic record rather than only a PDF. Technical transmission does not confirm that the exchange-rate or VAT logic is correct. See E-Transformation Services in Turkey for the electronic-document control environment.
A month-end reconciliation checklist for the accounting team
| Control | Evidence | Exception to investigate |
|---|---|---|
| Invoice-to-ledger | Currency amount, tax point, rate and TRY posting | Invoice and ledger use different dates or rates |
| Payment allocation | Bank statement and invoice matching schedule | One payment closes multiple invoices without a traceable rule |
| Realised difference | Settlement calculation by invoice and payment | Bank fees, short payment or credit note treated as FX |
| VAT mapping | Original VAT rate, exemption or withholding code | Generic VAT code applied to every exchange difference |
| Open-balance valuation | Foreign-currency ageing and official valuation rate | Valuation difference invoiced or duplicated |
| Counterparty agreement | Statement or balance confirmation | Customer and supplier ledgers close at different TRY amounts |
Common errors to correct before filing
- Using the invoice date automatically when the taxable event occurred on another date.
- Applying the bank's commercial rate without documenting why it is the agreed or legally relevant rate.
- Calculating VAT on the exchange movement attributable to the VAT amount itself.
- Issuing one net exchange-difference invoice across unrelated invoices without invoice-level traceability.
- Treating bank fees, withholding, credit notes or short payments as an exchange difference.
- Invoicing an unrealised period-end valuation.
- Applying domestic exchange-difference invoicing mechanically to a non-resident counterparty.
- Posting both the ERP's automatic FX entry and a manual adjustment, thereby duplicating the result.
If an error affects an already issued e-Invoice, a filed VAT return or an approved e-Ledger period, do not delete or overwrite the record informally. Determine whether the correction requires a new document, an accounting adjustment, an amended return or an authorised electronic-ledger procedure.
Reconcile the invoice, bank and VAT trail
Share the invoice register, open-item ageing, bank settlement report and VAT mapping. We can identify realised differences, period-end valuations, missing documents and cross-border exceptions in one review file.
Discuss the reconciliation on WhatsApp Call +90 538 239 76 19
Official sources
- Turkish Revenue Administration — VAT General Implementation Communiqué, current 2026 consolidated text
- Turkish Revenue Administration — Value Added Tax Law No. 3065
- Turkish Revenue Administration — Tax Procedure Law No. 213
- Turkish Revenue Administration — Private ruling on VAT treatment of exchange differences
- Turkish Revenue Administration — Private ruling on period-end exchange revaluation and VAT
Legislation and source check: 28 October 2026. This article provides general information. Private rulings address the applicant's facts and are not a substitute for transaction-specific advice. Confirm the underlying supply, contract, counterparty, VAT code, exchange-rate source and correction route with your Turkish tax adviser and certified public accountant.

Share this guide with your network
Choose a platform and share the article with its title, link and preview image ready.
Need advisory on this topic?
Contact us by WhatsApp or phone, or submit your request using the short form below.